
(Data as of June 2026)
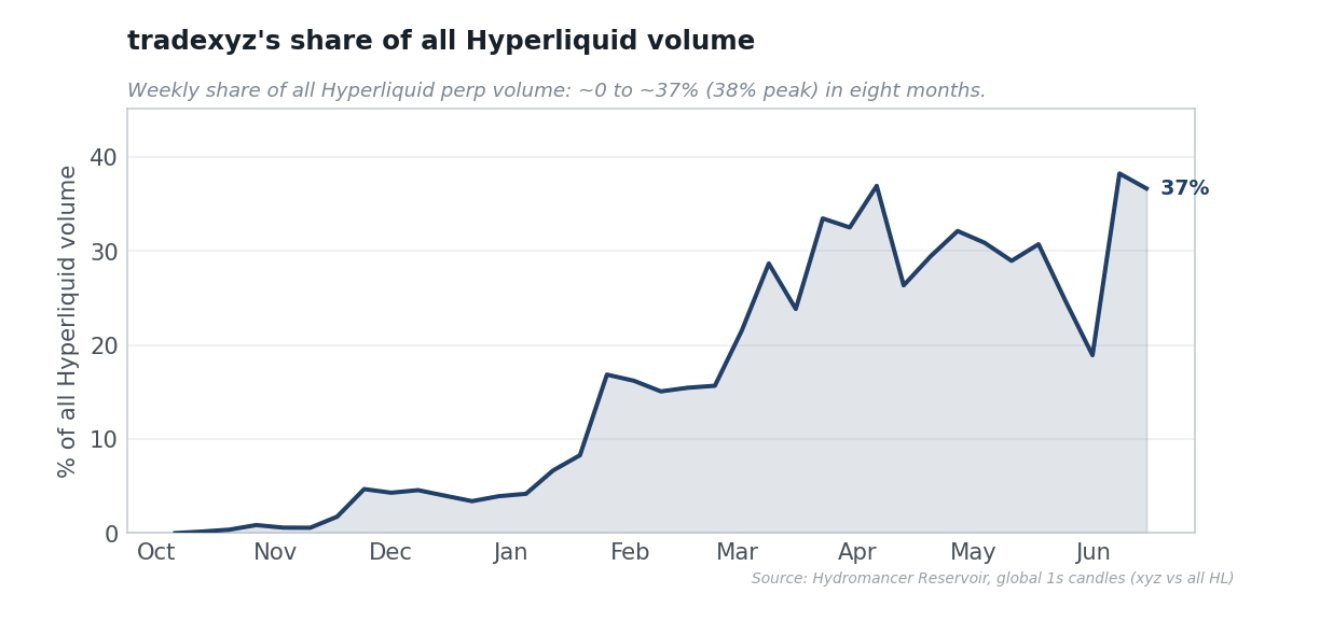
With every tick up in HIP-3 open interest, with every basis point jump in HIP-3 volume share, with every new pre-IPO listing, with every new tweet about how hyperliquid is leading price discovery for some of the world’s largest, and most in focus assets, the voice in everyone’s head gets louder.
Is Trade[XYZ] an existential threat to Hyperliquid? Has Hyperliquid given away the keys to the kingdom? Will HYPE die if Trade[XYZ] launches a token?
I am going to try and lay out a data backed and first principles reasoned opinion on why i think trade[xyz] is accretive to Hyperliquid, and in effect, HYPE.
The conventional case for @tradexyz being good for Hyperliquid is narrow: it locks HYPE, lists and runs new markets, generates trading fees, and routes those trading fees into HYPE buybacks. While that is true, in my opinion, it understates the relationship between Hyperliquid and the deployer, and in this case, @tradexyz. The reality is that Tradexyz, has, in eight months, built the single hardest thing in this category: a genuinely liquid market in equity, index, commodity and FX perpetuals, and in doing so, has proven that HIP-3 can host a specialist-built, institutionally liquid non-crypto perp vertical while Hyperliquid keeps the users, matching engine activity, fee share, auction demand, and ecosystem narrative, without taking direct listing/regulatory liability.
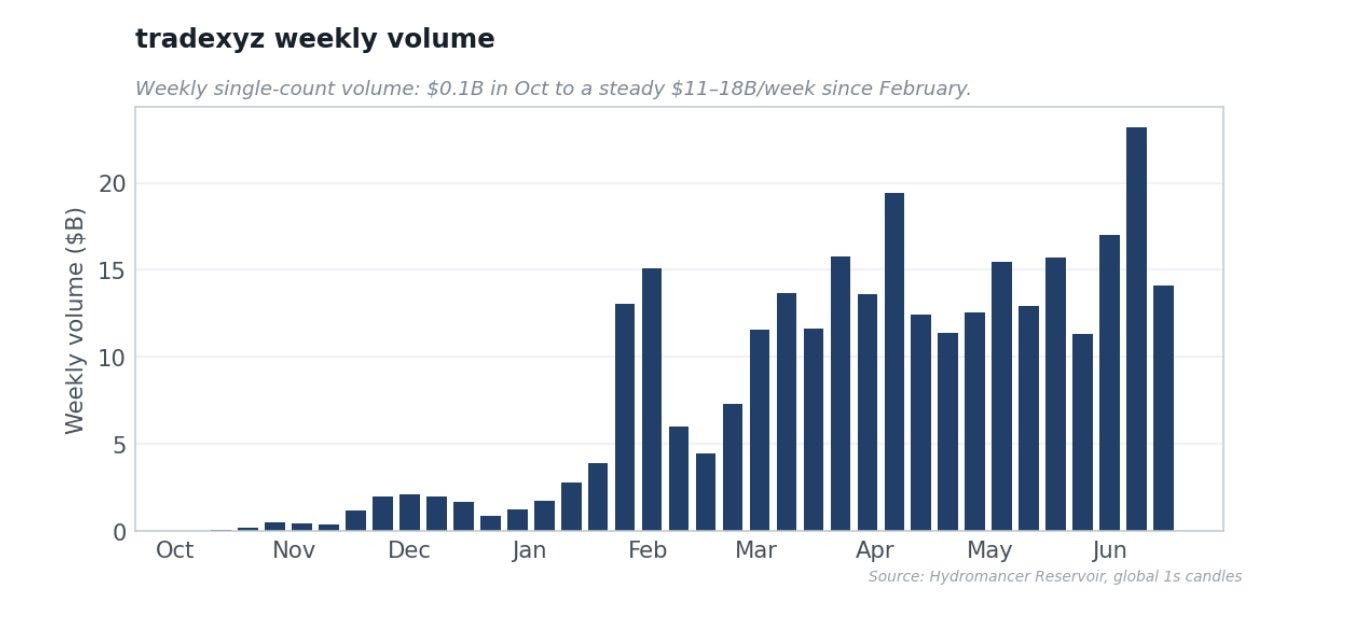
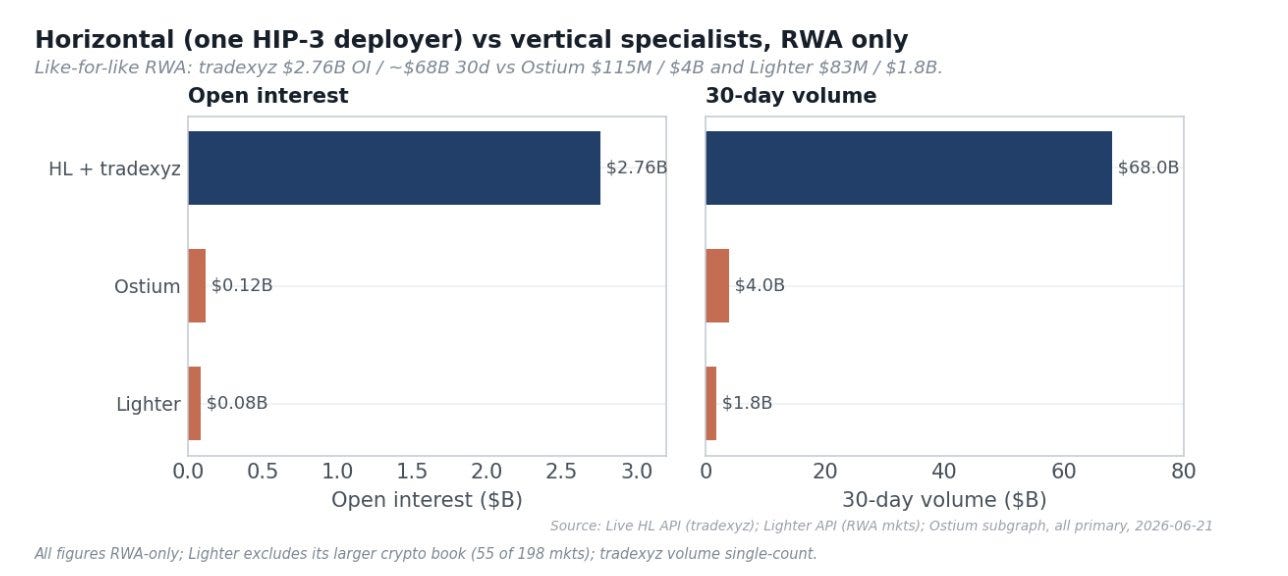
There are two ways to grow a derivatives venue. The vertical path is to build every market yourself, source the assets, run the oracles, recruit the market-makers, carry the risk, and keep all the economics; Lighter and Ostium (RWA-only) are vertically integrated products. The horizontal path is to provide the base layer and let permissionless deployers build the markets on top, splitting the fees; this is Hyperliquid’s HIP-3, and @tradexyz is one deployer. But it is a mistake to read HIP-3 as horizontal for the sake of being horizontal. The way I think it should be looked at is, as request for access.
Hyperliquid’s conviction is that the durable edge in on-chain finance is the core infrastructure, the L1, the clearinghouse, the matching engine, and that is where the core team spends nearly all of their effort. The bet is that the best operators will choose to build on that infrastructure, and to attract the best operators, it needs to constantly build towards being high performance, and neutral.
There is only one CME, one NYSE, one Hong Kong stock exchange. Liquidity begets liquidity, and a category without a single deep-liquidity winner has, in effect, already lost. Hyperliquid’s ambition is to be the house of all finance, the neutral substrate on which the winner of each category is built, and HIP-3 is the mechanism for getting there. Rather than crown a winner, it opens the rails, invites the best operators to compete to build the deepest market, and lets liquidity itself decide. The eventual winner drives enormous value back to Hyperliquid: fees, buybacks, users, while keeping a real prize for itself. In this view, concentration is not a failure of the model; it is the model working the way finance has always worked.
There are a lot of objections to this model though, and I guess they deserve a fair hearing.
The first is that Hyperliquid is giving away future value, and by letting deployers keep roughly half the fees and own the franchise, it forfeits economics it could have captured by building equity perps itself. The second is harsher, that HIP-3 is vertical integration in disguise. One deployer does ~98% of HIP-3 volume, prompting accusations of favouritism (often pointing to tradexyz’s perceived ties to the Unit ecosystem), while Hyperliquid still takes 50% of the fees.
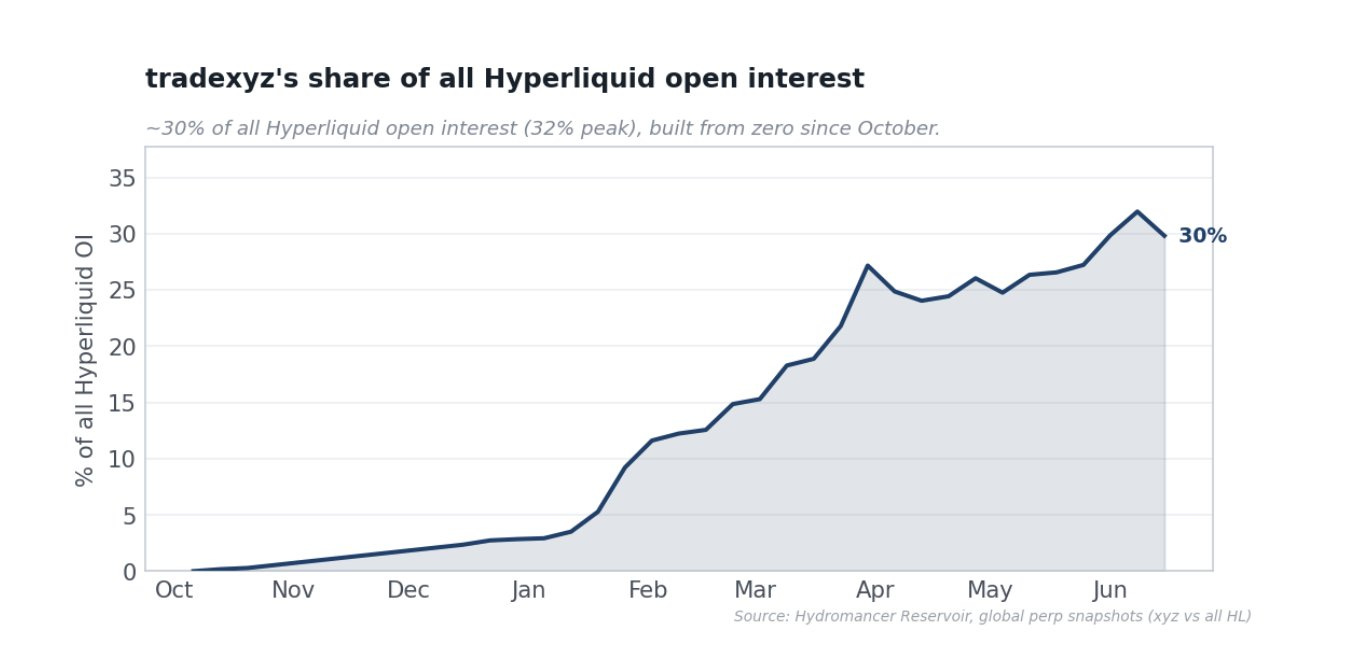
My view is that this vastly underestimates how hard it is to stand up institutional-grade real-world-asset markets. The whole goal of this report is to present a data backed, first principles analysis of whether this current model is even remotely successful or not.
What It Actually Takes To Build An Equity Perp Market
“Just list the assets” is the most common misreading of this business. Listing is the easy part; the difficulty, and the moat, is making a newly listed market tradeable in size. Tradexyz’s data speaks to three distinct hard problems:
1. Listing fast enough to catch demand
2. Sourcing the market-makers that create depth
3. Keeping that liquidity economically real and operating those markets day to day.
Listing Pace
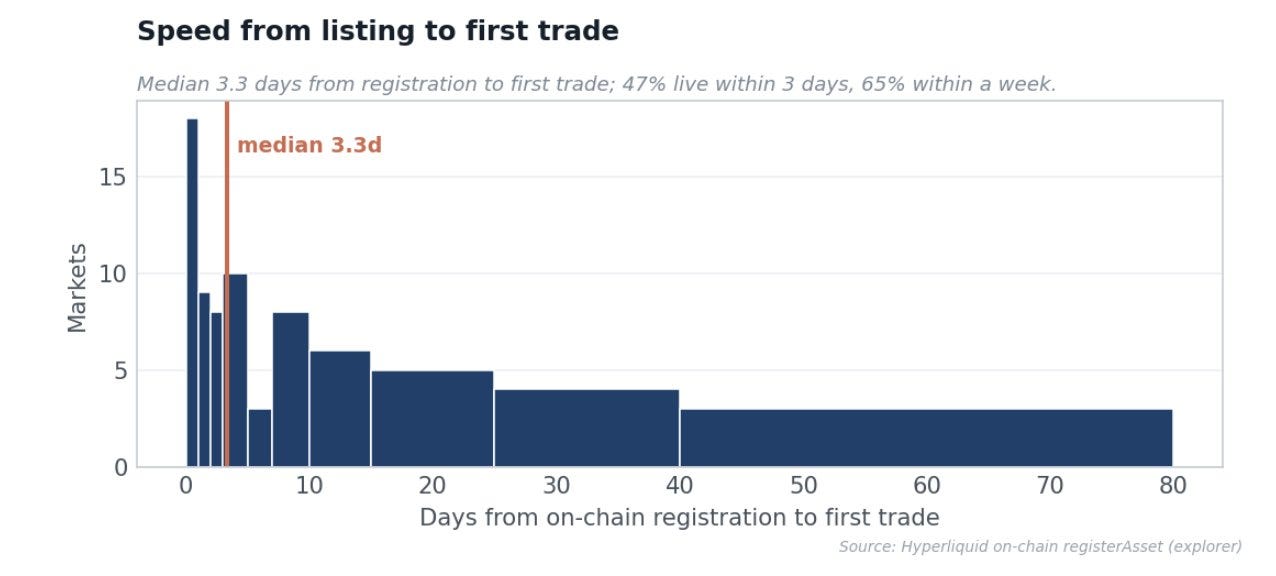
A perpetual market is only valuable if it exists when a trader thinks of it. Measured precisely from the on-chain registration of each asset to its first trade, tradexyz’s median time-to-listing is just 3.3 days, with 65% of markets live within a week and 47% within three days.
Tradable Markets Are The Real Moat
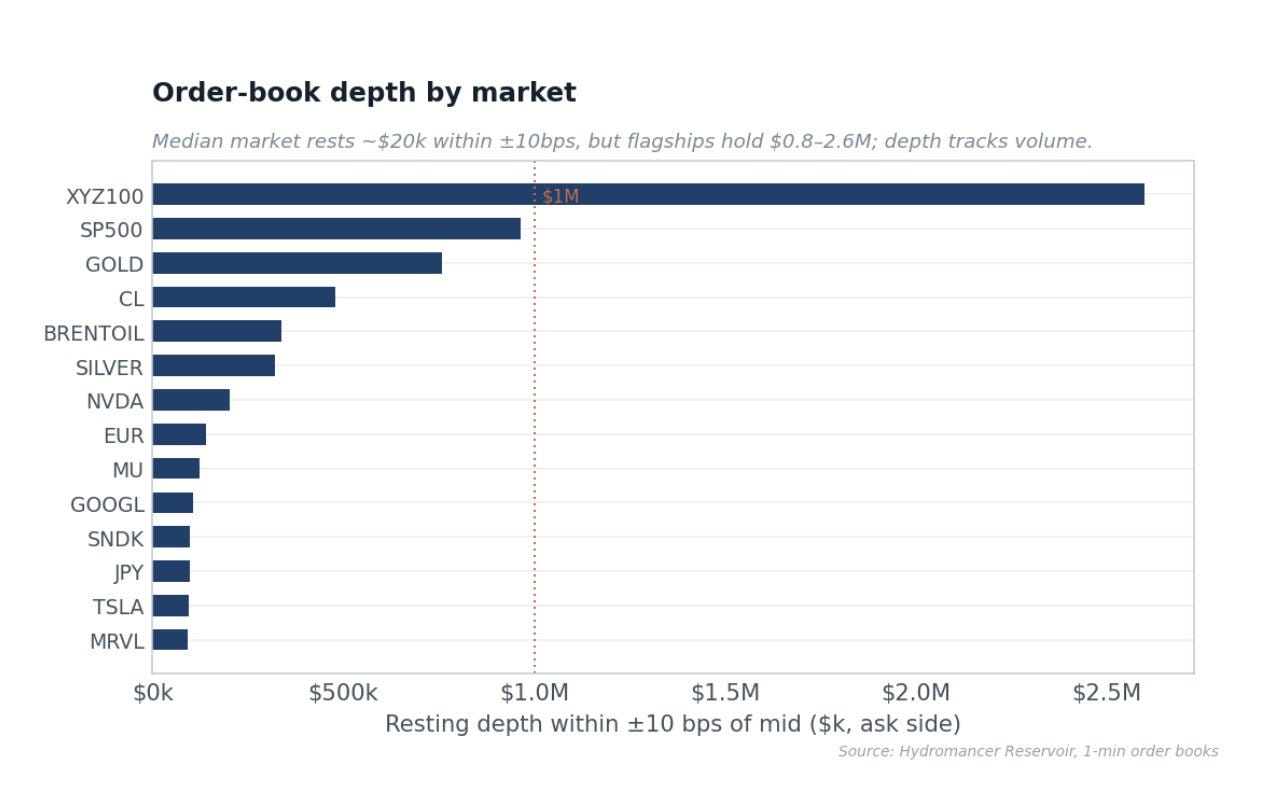
Tradexyz’s depth is both deep and rationally distributed. The flagship index and commodity markets carry institutional-grade resting depth, XYZ100 rests $2.6 million within 10bps of mid, the S&P 500 market $964k, gold $759k, while single-name equities such as NVIDIA and TSLA hold enough for comfortable working size. The median market, by contrast, rests only about $20k within 10bps. This is how rational market-makers allocate capital.
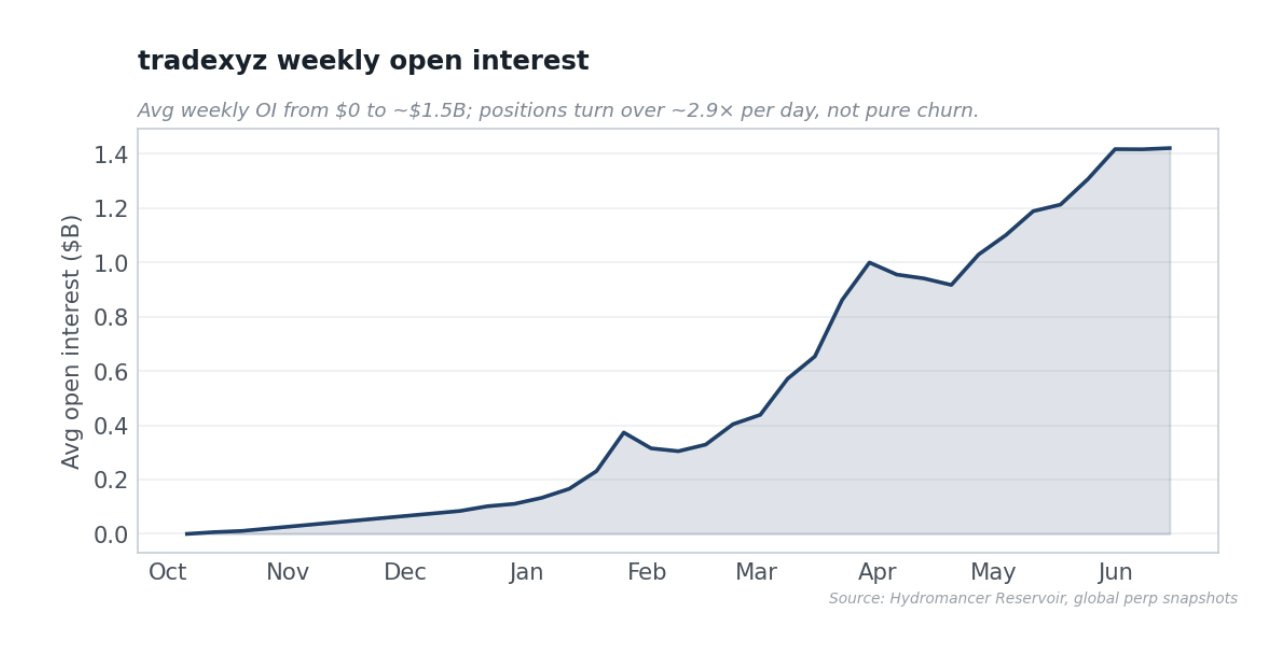
Securing market-makers is the actual skill, and market-maker presence is what tightens a market. Across the 73 markets with sufficient data, the number of distinct daily maker wallets is correlated with spread at −0.72, volume with spread at −0.82, and volume with open interest at +0.96. The volume-weighted average spread across the book is 2.33bps and daily turnover runs at roughly 2.9x OI. Tradexyz’s edge is the BD work and capital work of securing market-makers, and that work is what produces tight, deep markets.
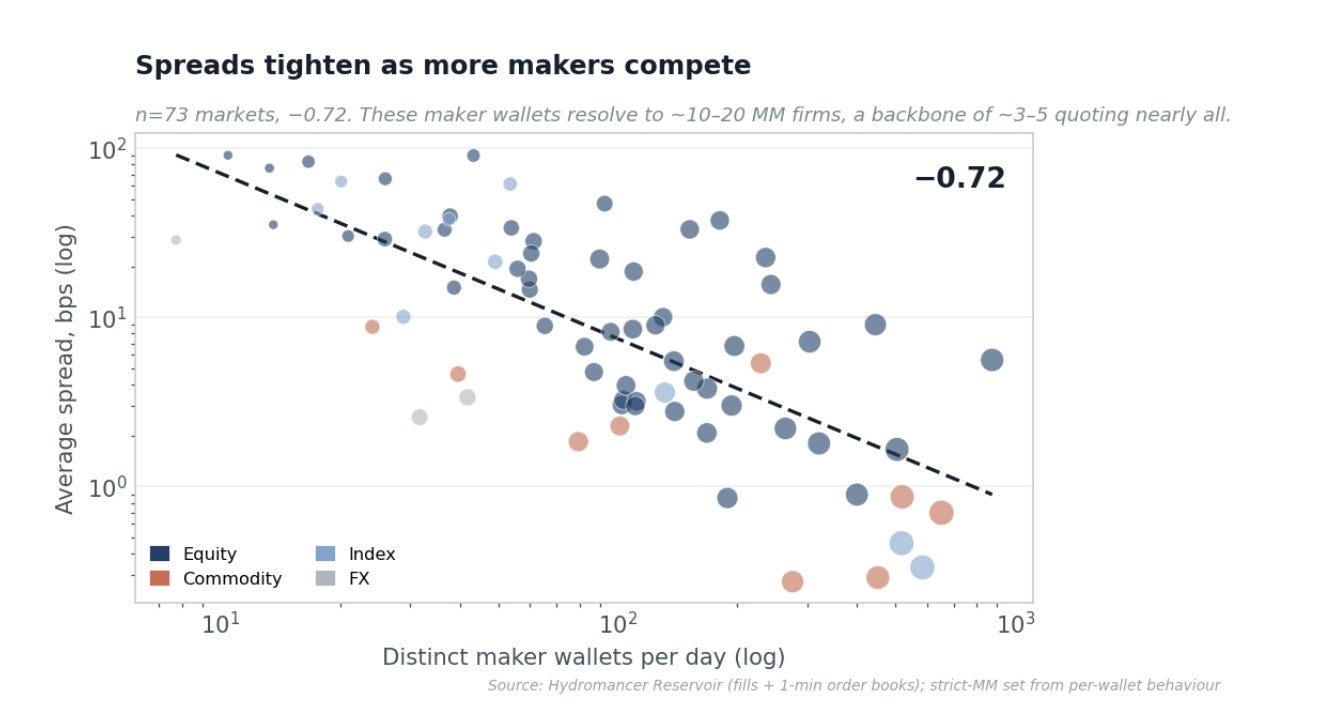
It is worth asking, from first principles, why securing this liquidity is the hard part, and why one only one deployer has succeeded in caling these markets well. A market-maker earns the spread but survives only by managing what each fill leaves on its book. To put it simply, MMs need a way to hedge.
The main risk is plain inventory risk: every fill leaves the desk long or short, and an unhedged trend is a big red flag. The crux for equities, is hedging. A crypto perpetual can be hedged on another crypto venue around the clock, but an equity perpetual’s only true hedge is the underlying stock, ETF or future, which trades only while the cash market is open. During regular hours a desk can hedge its TSLA-perp inventory with TSLA stock and captures the spread almost risklessly, so it can quote tight and deep. But once the market closes, it is warehousing naked inventory, and the rational response is to widen, thin out, or stop. Before an IPO there is no hedge at all, which is why those books are thin until listing. On top of this sit adverse selection (a larger share of off-hours flow is informed), funding and carry (the funding rate must tether the perp to its index without making the hedge uneconomic), and oracle or gap risk (the perp settles against an oracle, and a stale, manipulable or gapping mark is uncontrollable liquidation risk that makes the book un-makeable at size).
So the real skill is not listing a ticker; it is having the hedging pipes, a pricing and risk framework that keeps inventory manageable even when the hedge is unavailable, and the capital to stand behind both. This is precisely where tradexyz’s design lives, and each mechanism maps onto one of those risks while doing something concrete for the market-maker. Its oracle runs around the clock by switching from external to internal pricing: when the cash market closes, the oracle advances by a continuous exponentially-weighted moving average with a 30-minute time constant for equities (each update clamped to about 9.5% of the gap), and for indices it discounts the futures price at an EMA discount rate, keeping a sane mark when no external price exists.
In plain terms, even at 3am with Nasdaq shut, the perp still carries a sane, smoothly-moving reference price that cannot lurch on a single print, so the desk can keep quoting without fearing that the mark suddenly jumps and liquidates inventory it cannot yet hedge. The mark price is then the median of three inputs (the oracle; the oracle plus a 150-second EWMA of perp-mid-minus-oracle; and the median of best bid, best ask and last), with relayer updates clamped to plus or minus 50bps. No single bad feed or spoofed quote can mark the desk’s book against it, because an outlier input is outvoted by the other two and the clamp caps how far any one update can move the price.
Discovery Bounds hold the mark within plus or minus one over the maximum leverage of a reference price (about 5% at 20x), re-anchoring in discrete, per-market-capped steps and becoming a hard cap until external pricing resumes, paired with liquidation protection that prevents a position from being liquidated while its liquidation price sits outside the active bounds. Put simply, there is a “known ceiling” on how far price can travel in a single move, and the venue will not liquidate the desk while that ceiling holds, so the worst case on unhedgeable overnight inventory is bounded and quantifiable rather than open-ended. Finally, a per-market funding multiplier scales standard funding by 0.5 (about a 5.5% annualized baseline) but drops to 0.005 for pre-IPO names. Funding keeps the perp tethered to fair value without sucking the MM dry, and for pre-IPO names with no stock to arbitrage against, it is turned almost all the way down so that simply holding a position there is not unprofitable. Together these are a toolkit for making markets that first principles say should be unmakeable once the hedge is gone.
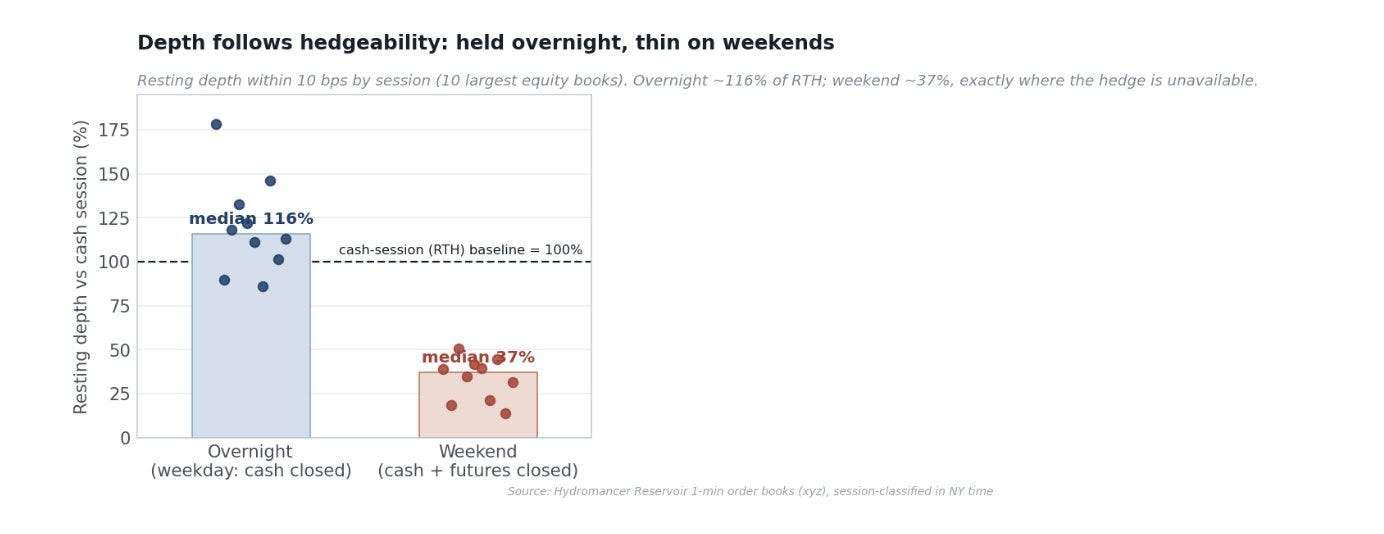
Measuring resting depth by session across the ten largest equity books, overnight depth holds at roughly 116% of the cash-session level, with single names such as Nvidia and Tesla actually deepening, because once the cash market closes the perpetual is the only live price and quoting concentrates there. On weekends, when even index futures are shut and the hedge is gone for two full days, depth thins to about 37%. One boundary should be stated honestly: this makes tradexyz’s off-hours book resilient, not magically superior. The durable differentiators remain its daytime depth, its order flow and the breadth of genuinely hard-to-make markets. What the data does support is that tradexyz’s risk machinery lets market-makers retain depth overnight where first principles predict a collapse, which is itself the non-trivial engineering that makes these markets makeable at all.
TradeXYZ Doesn’t Run A One-Time Listing Biz
Tradexyz does not list and walk away. In its most recent window of roughly 300 onchain actions, it performed 294 distinct risk-management operations. 54 open-interest-cap changes, 35 growth-mode toggles, 34 funding-multiplier adjustments, 28 trading halts and 11 margin-mode changes, alongside per-asset annotations. This is continuous, per-market risk management across 92 underlyings with real trading hours, halts and funding to handle, a full-time market-operations business.
The difficulty is best appreciated by comparison. Tokenized spot equities on Solana (xStocks) represent over $25B in total transaction volume, but only ~$517M of actual DEX trading volume. Ostium, a dedicated and funded RWA-perp DEX, has accumulated ~$59B of cumulative volume but holds only ~$115M of OI, 24x less than tradexyz’s. Newer entrants such as Variational do not even attempt to build native depth, instead aggregating liquidity from Hyperliquid, Lighter and centralized venues by RFQ, routing toward Hyperliquid for the very liquidity in question. The category leader in onchain equity perps, by a wide margin, is tradexyz-on-Hyperliquid.
TradeXYZ Markets Expand the HL Userbase, Hyperliquid Benefits from Its Network Effects
A natural assumption is that a deployer owns its users through its own frontend. The opposite is true. Tagging every fill by the frontend (builder) code that generated it, measured on the taker leg, the side that selects the frontend, shows that about 97% of volume in tradexyz’s markets is traded through Hyperliquid’s own application and API, with all third-party frontends combined accounting for ~3%, and tradexyz’s own frontend only a sliver of that. In other words, almost every trade on tradexyz’s products happens on Hyperliquid’s surface.
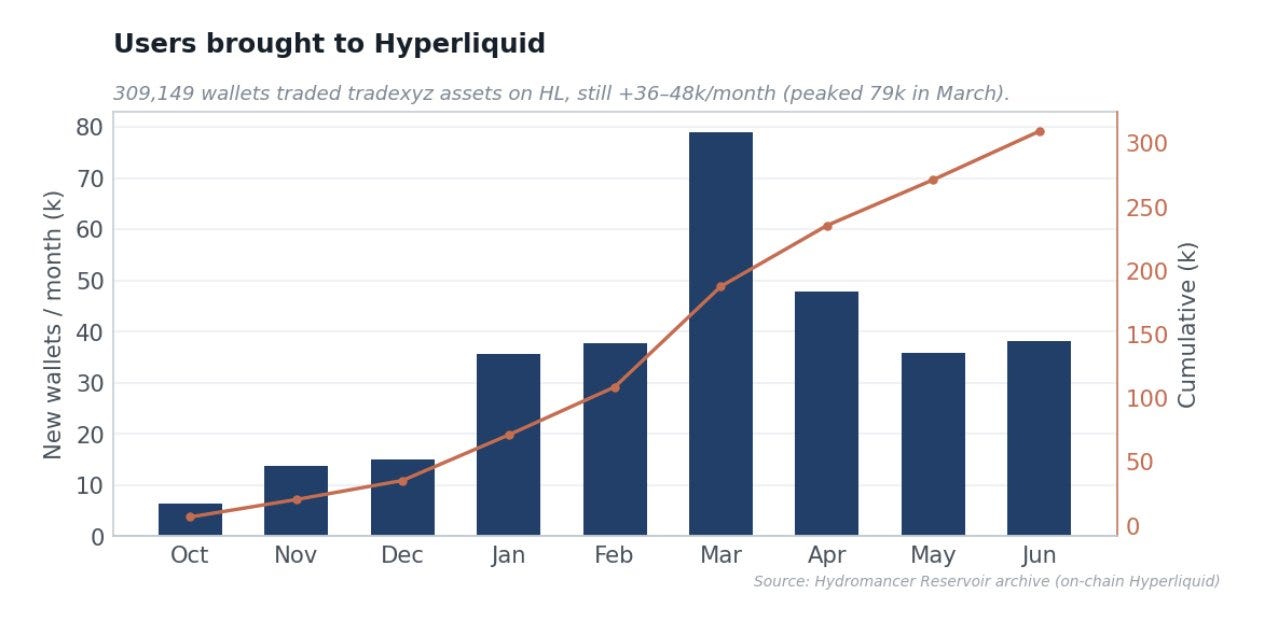
The acquisition this represents is substantial and ongoing. Tradexyz has cumulatively brought ~300K+ distinct wallets onto Hyperliquid, and it is still adding between 36,000 and 48,000 each month, having peaked at nearly 79,000 in March during the listing and SpaceX surge. Equity and RWA perpetuals function as a top-of-funnel acquisition channel: the assets are the lure, and Hyperliquid is the venue where the resulting users land, trade and stay. This is real attention and user-acquisition value that never appears in a fee table.
Incentives At The Protocol Level Are Correctly Aligned
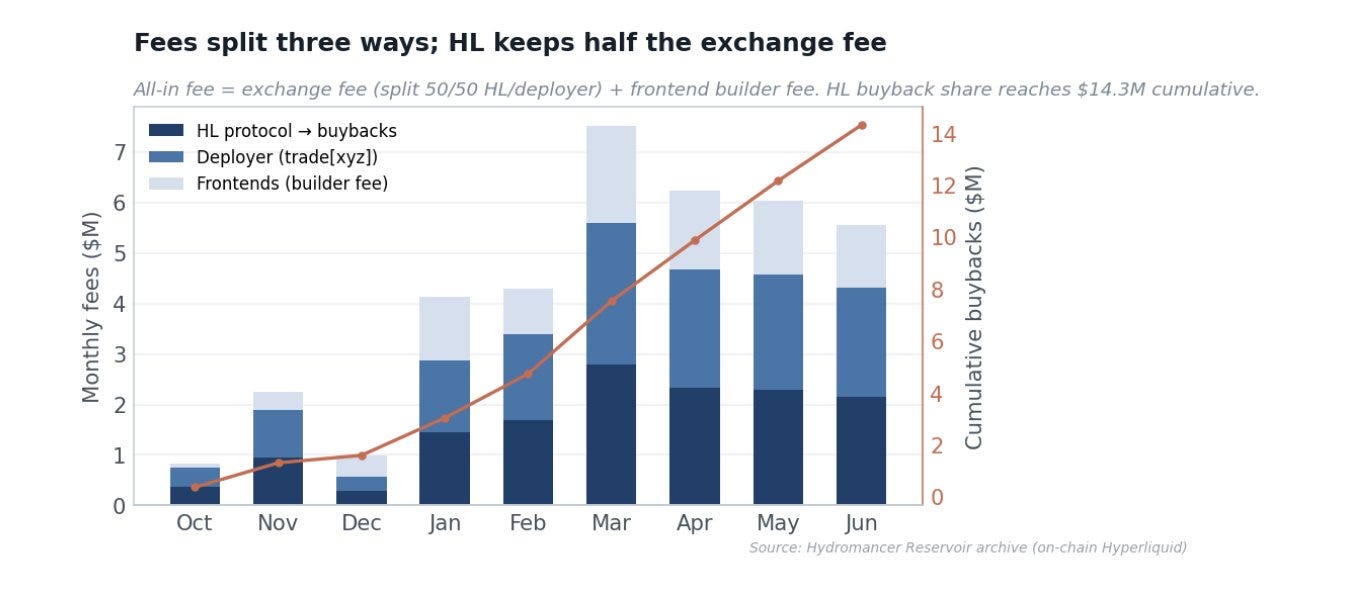
All-in HIP3 trader fees total about ~$37.9 million, and they split three ways. Builder-code fees of about $9.2 million go to third-party frontends and are not the deployer’s; the remaining exchange fee splits 50/50 between Hyperliquid and the deployer. So Hyperliquid’s protocol share, directed into HYPE buybacks, is about $14.3 million, and the deployer’s share is about $14.3 million accrued. HIP-3 caps the deployer’s share, and Hyperliquid’s protocol fee matches any deployer share above 100%, so a deployer can never take more than half. Cheap, deep markets attract the size that generates the fees in the first place.
My Thoughts On Growth Mode
A HIP-3 deployer chooses a fee mode for each market: standard charges 9bps to the taker and 3bps to the maker, while growth charges 0.9bps and 0.3bps, a ~90% reduction. Growth Mode is reserved for non-crypto real-world assets and explicitly excludes crypto wrappers such as MSTR and, notably, GOLD, because of its overlap with the existing PAXG-USDC market. This exclusion hands us a clean natural experiment.
Today the growth-eligible book runs near 0.86bps while the excluded names run near 7bps, an 8x gap on the very same matching engine.
RWA perps compete with traditional-finance all-in costs. A nine-basis-point fee is uncompetitive against CME index futures or cash-equity commissions, whereas 0.9 is competitive and trades around the clock with leverage. Cheap, deep markets are how a land-grab is won and the depth and market-maker backbone is formed. In a category that tends toward a single winner, maximizing volume, open interest, users and reference-price status is valuable.
Yet, growth mode is not why the volume is here, and three data points show it. First, the onchain control: six of the seven other HIP-3 deployers had the identical fee tools and did essentially zero volume, and the number-two deployer (dreamcash) even quotes tighter spreads yet remains roughly 30x smaller; if cheap fees made volume, dreamcash would be close. Second, the GOLD experiment: GOLD pays about 8x the fee of the growth book yet is the single largest fee market and a top-three market by volume and open interest. Traders pay full freight for GOLD because the liquidity is there.
Which is why switching it off would not kill volumes; it would route more value to HYPE. Because the exchange fee splits fifty-fifty in both modes, raising it lifts value to HYPE by roughly 9x to 15x (growth ~0.9 bps to standard ~9–12 bps), so even under heavy volume attrition Hyperliquid’s buyback share rises unless volume collapses by more than about 85%.
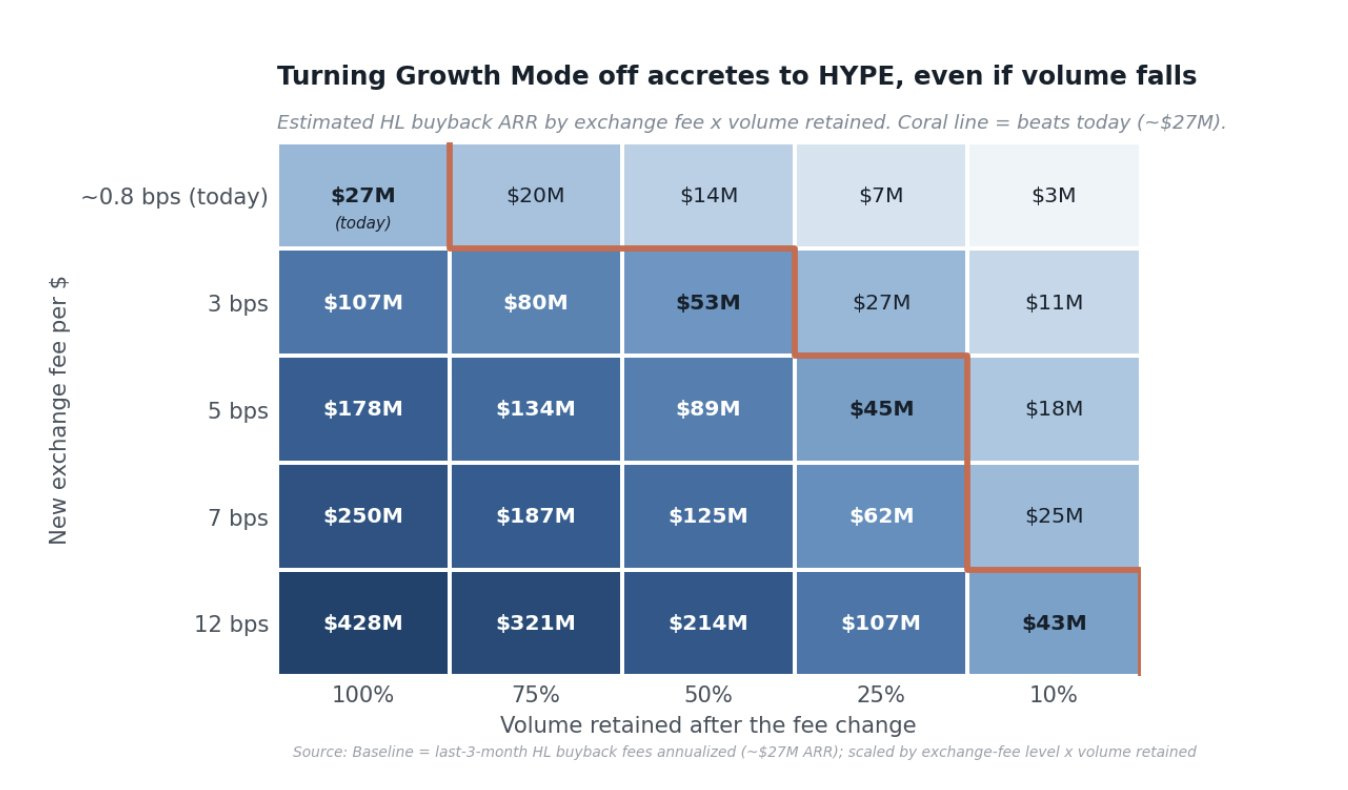
At GOLD’s observed 7bps, tradexyz would need only about 11% of today’s volume to match today’s buybacks (about 15% at 5bps, 25% at 3bps). A realistic monetization, moving mature markets to five-to-seven basis points while retaining half to three-quarters of volume given the moat, would send roughly $90–185 million a year into buybacks, 3-5x more than current rates. And this is not hypothetical: GOLD already runs at standard fees and turns 4.3% of volume into 23% of all buybacks. The growth-off scenario observed live on a single market, and proof that a deep real-world-asset market keeps trading at standard rates, so a collapse beyond 85% is unlikely. The two phases are one strategy, grow the moat cheaply now and monetize it later, and both route value to HYPE: first as users, volume, open interest and reference-price status, then as fees.
Per Market Dynamics
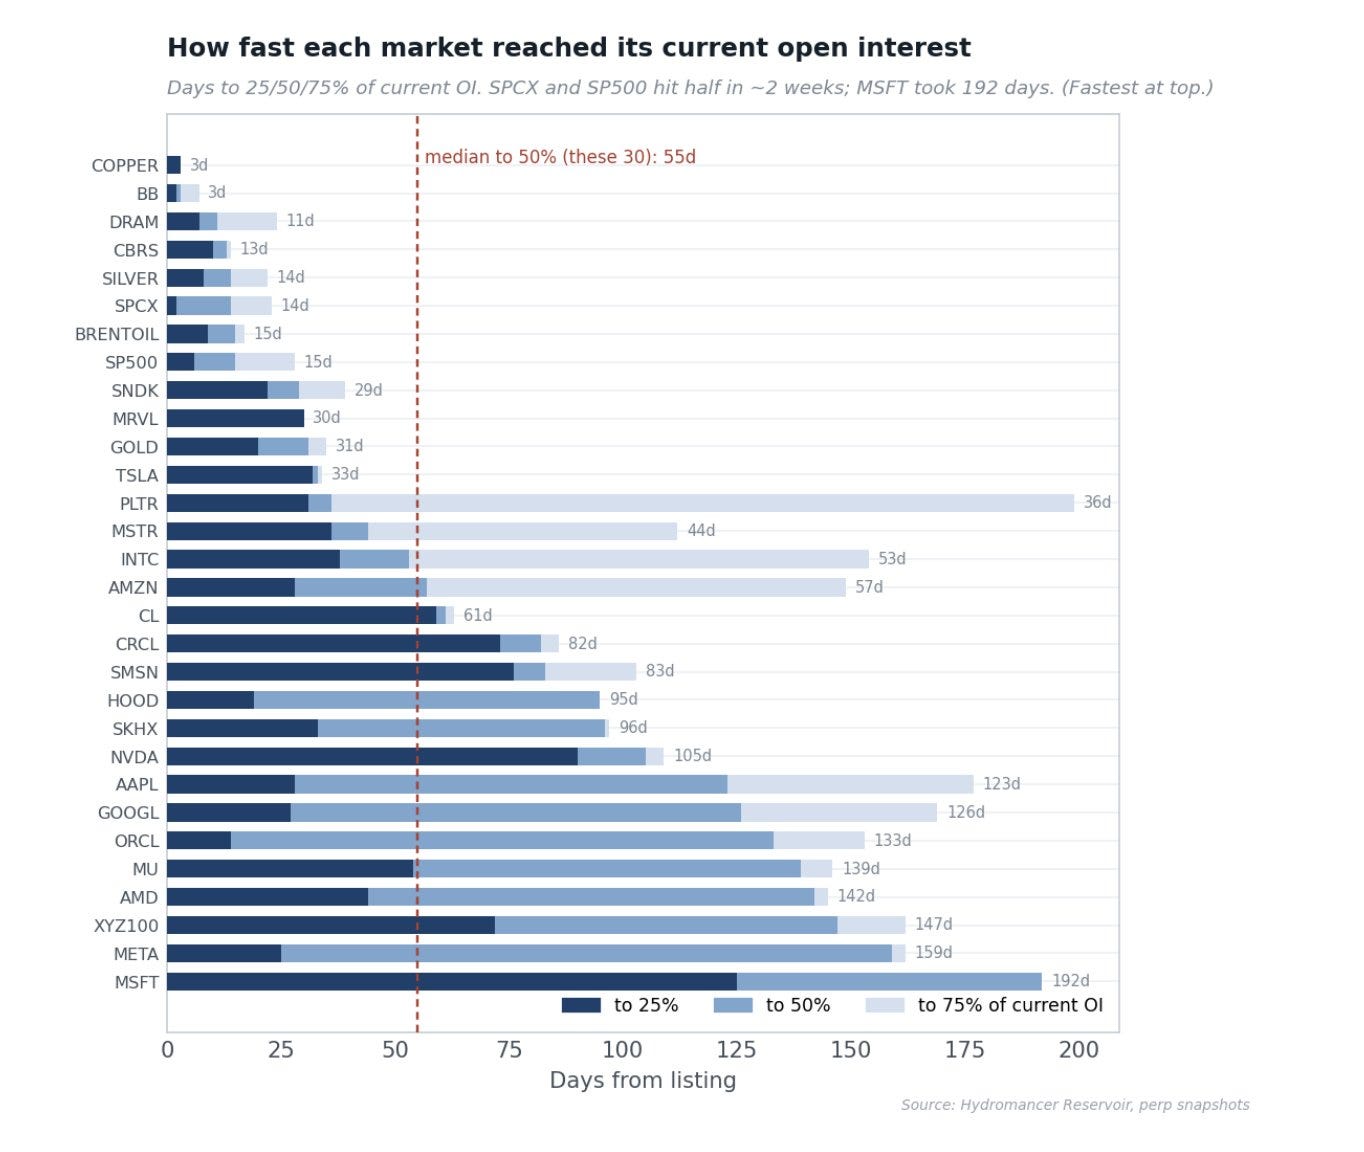
The top 30 markets hold roughly 95% of OI, led by the S&P 500, the XYZ100 index, Brent crude and WTI. More interesting than the level is the speed at which each market got there. Measuring, for every market, the days from listing to 25%, 50% and 75% of its current open interest, the median market reaches a quarter of its eventual size in 9 days, half in 15, and three-quarters in 30, but the spread is enormous and revealing. The fastest markets reach half their current OI in roughly two weeks (SpaceX in 14 days, the S&P 500 and silver in ~15), while the earliest single-name equities, listed when the venue’s liquidity infrastructure was still nascent, took five to six months (Microsoft 192 days, Meta 159). That gap is the deployer’s learning curve made concrete: markets launched recently ramp far faster than the early cohort did, because the market-maker relationships and tooling now exist on day one.
Proof Of Market Quality
A. MM Concentration By Market Over Time
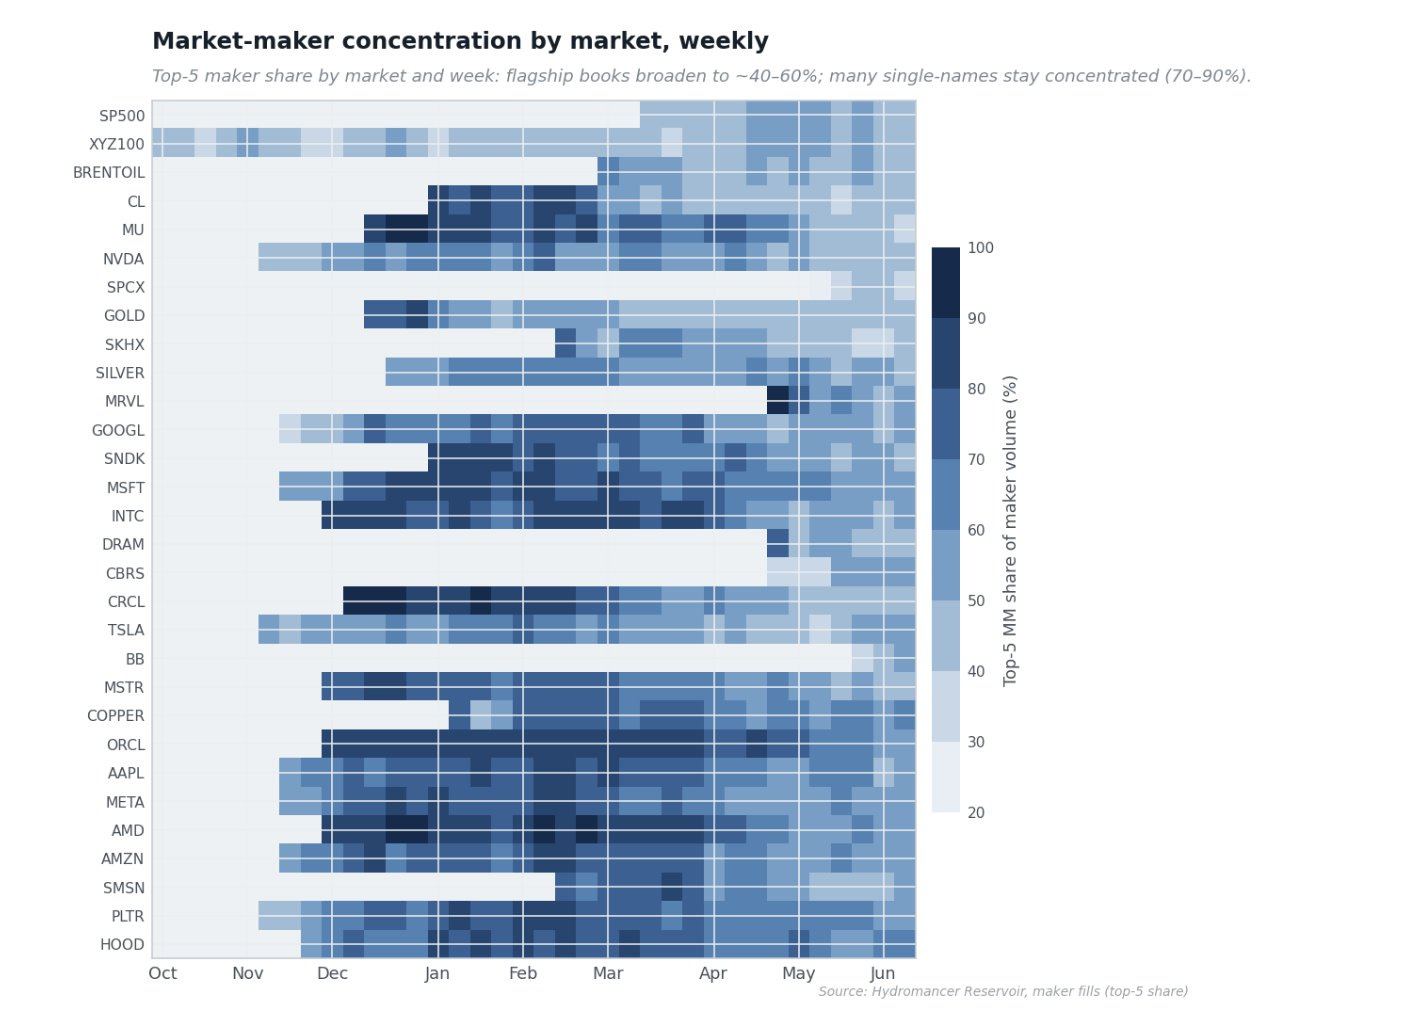
Liquidity provision has broadened as the Tradexyz has matured. The heatmap below shows, for each market and week, the share of maker volume captured by its top five market-makers. The early markets are deep blue, in their first months a handful of market-makers supplied almost all the passive liquidity (top-five shares above 90%). Over time the largest, most liquid markets lighten as more market-makers compete to quote them, while many single-names stay concentrated. A more concentrated book is not inherently worse, it is how a market is bootstrapped, but the flagships becoming contested is a healthy sign that liquidity provision on tradexyz is now a competitive business at the top of the book rather than a favour from one or two MMs.
B. The MM Backbone
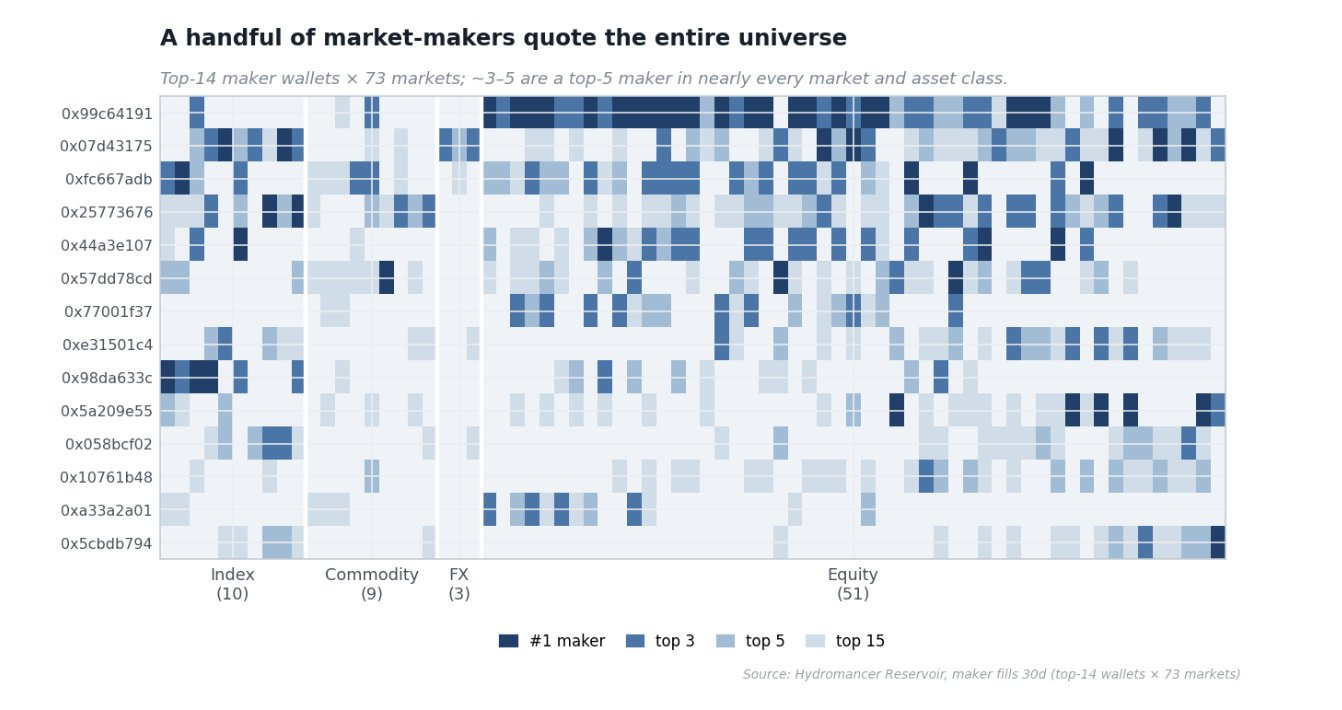
A natural question is whether a small number of firms quote the entire universe rather than each market attracting its own specialists. Ranking the top makers in every market over 30 days and asking which wallets recur at the top across markets reveals a distinct backbone. The single largest backbone wallet is a top-five maker in 47 of 73 markets and the number-one maker in 22; the top three backbone wallets are together a top-three maker in 57 of 73 markets. Several of these wallets quote all four asset classes at once, equities, commodities, FX and indices, and all carry the textbook market-maker signature: directionality within a fraction of a percent and realized PnL within a rounding error of zero.
Where The Fees Come From
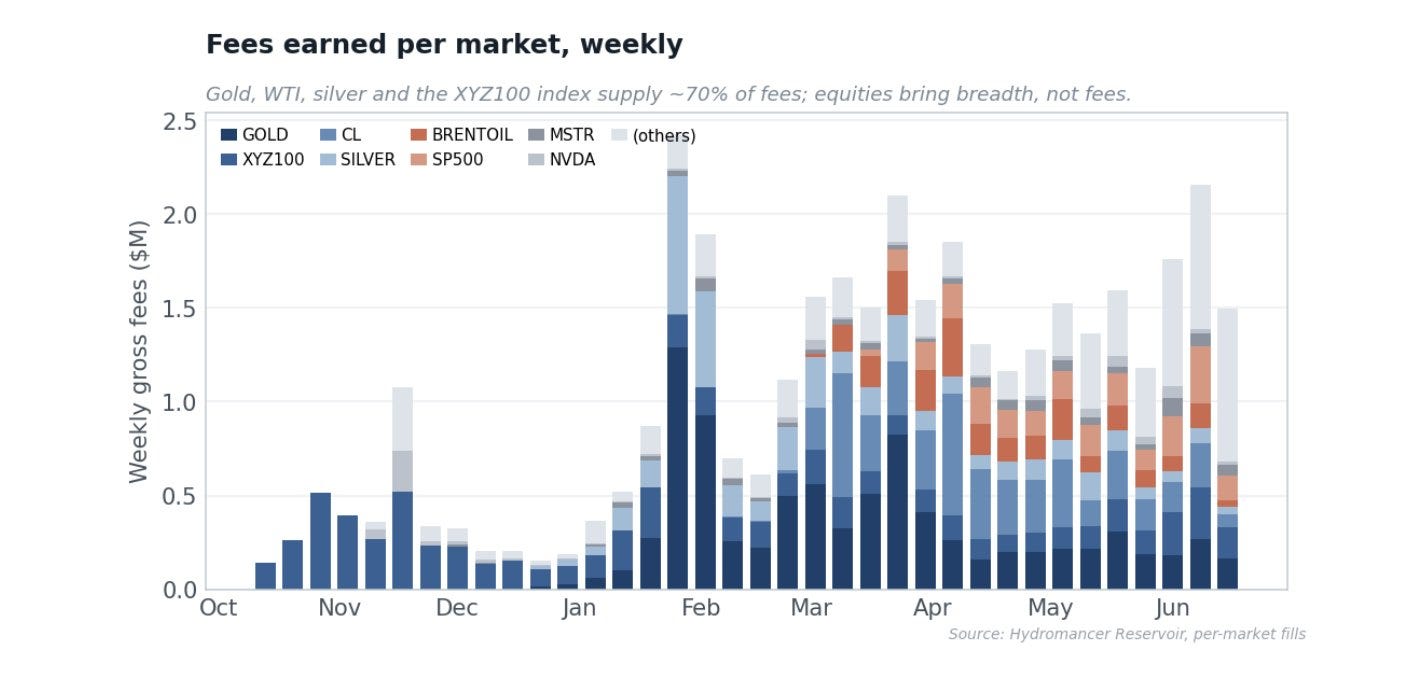
The fee base is commodity and index-driven. Commodities alone account for 54% of all fees earned, indices another 24%, and the entire long tail of single-name equities and FX just 22%, even though equities are the bulk of the listings. Gold is the single largest contributor at 23% of fees ($8.7M), followed by the XYZ100 index (18%), WTI crude (13%) and silver (10%); the top ten markets generate 84% of all fees.
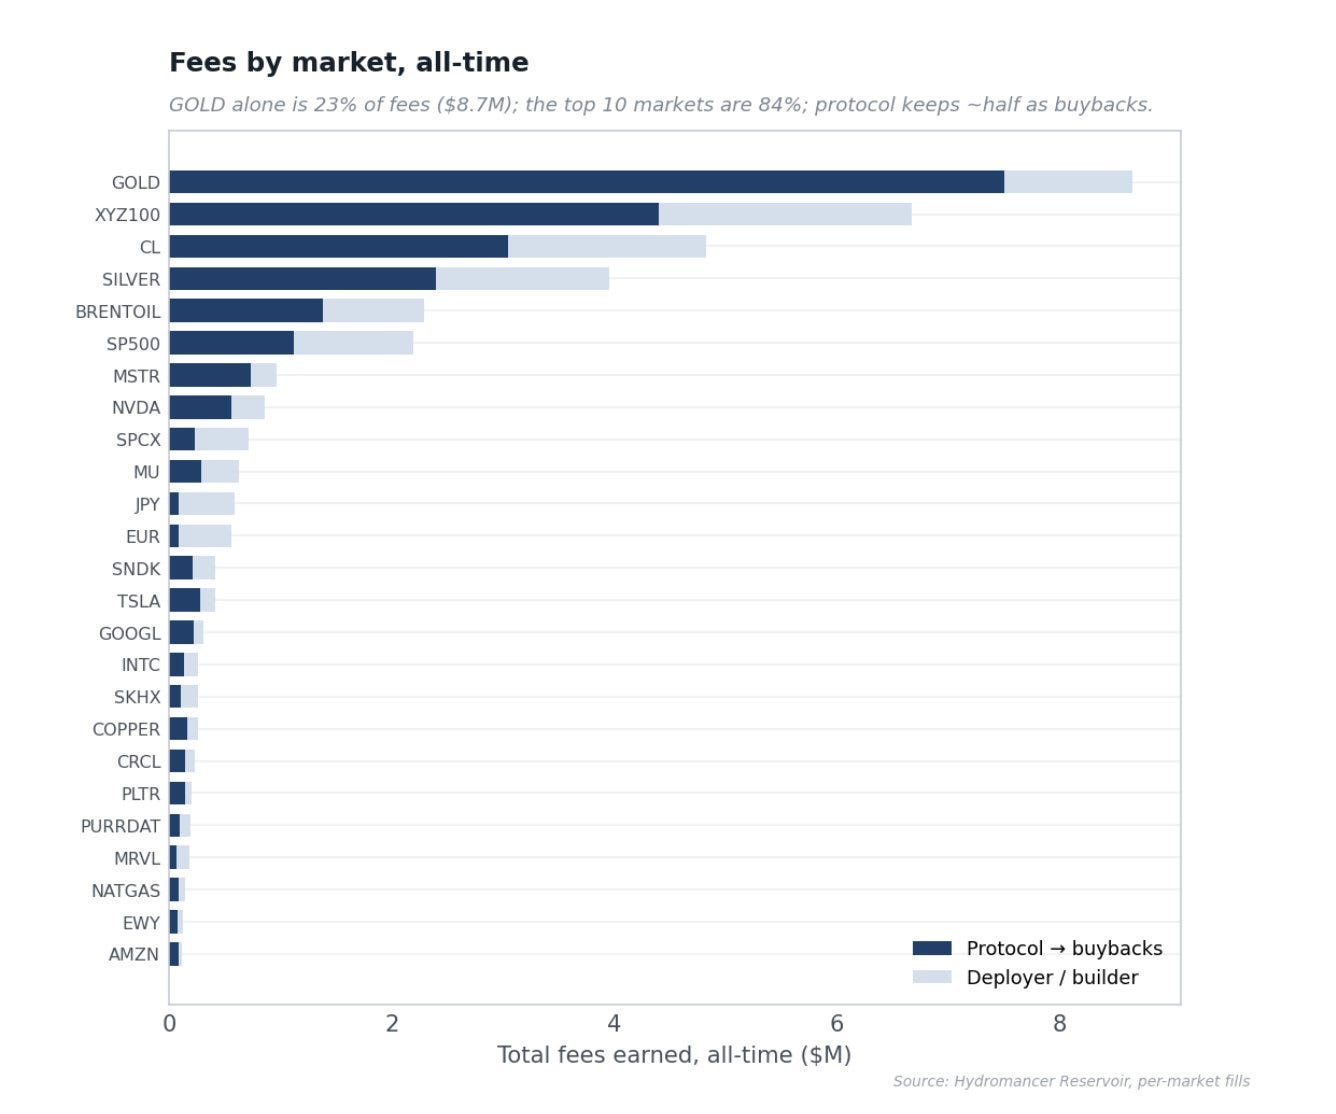
One nuance that GOLD forces, and it bridges back to growth mode, is that a fee ranking is not a volume ranking, because the fee mode differs by market. GOLD is the one large market excluded from growth mode, so it pays around seven basis points while the rest of the book pays around one, and that alone makes it the number-one fee market: it is 23% of all fees from just 4.3% of volume. By trading activity, GOLD is a minor market; by buyback fuel it is enormous.
Could The Core Team Have Done This Themselves?
My assessment is that they could not, and, more importantly, that they should not have. The strongest reason is regulatiry. Listing perpetuals on NVIDIA, TSLA and pre-IPO SpaceX sits squarely in securities-derivatives territory, and HIP-3 deliberately externalizes that liability to the deployer. Were the core team to list equities itself, it would place the protocol, the foundation and HYPE directly in regulators’ line of sight. Keeping listing at arm’s length is not a missed opportunity; it is the design.
The remaining reasons compound that one. Hyperliquid’s value rests on being credibly neutral infrastructure, and a core team that hand-picks assets undermines both the permissionless thesis and the deploy-auction fee market that HIP-3 exists to monetize. Running ninety-two equity, FX and commodity markets, sourcing oracles, handling market hours and halts, cultivating market-makers and performing the hundreds of risk actions visible on-chain, is a full operating business orthogonal to building a high-performance exchange, and securing best-in-class market-makers for niche real-world-asset perps is relationship and capital work rather than protocol engineering, exactly where even funded specialists move slowly. The empirical record settles it: if this were easy or doable in-house, one would expect either the core team to have done it or many strong deployers to exist. Instead the second-largest deployer is 46 times smaller, the focused standalone RWA venues are twenty-four to thirty-three times shallower, and new entrants route back to Hyperliquid for liquidity. Scarcity is the proof of difficulty.
I would like to end this blog with an analogy that hit home hardest to me.
What Tether has done for global access to the US Dollar,
is doing for global access to global equities.
All the data in the article is courtsey of the chads at